AMD's datacenter segment posted revenue of $6.7 billion in the second quarter of 2026, an increase of 107 percent compared to the same period a year earlier, when the company reported $3.2 billion. Compared to the first quarter of 2026, when the division generated $5.8 billion, this represents a further acceleration. Growth is driven by sustained demand for computing capacity for AI applications.
At the same time, the gaming division contracted by 31 percent. The contrast within the company is now wider than ever: the datacenter segment is pulling results upward, while gaming continues to decline. CEO Lisa Su and CFO Jean Hu commented on the figures in the quarterly report.
Major deals with Anthropic and Core Scientific
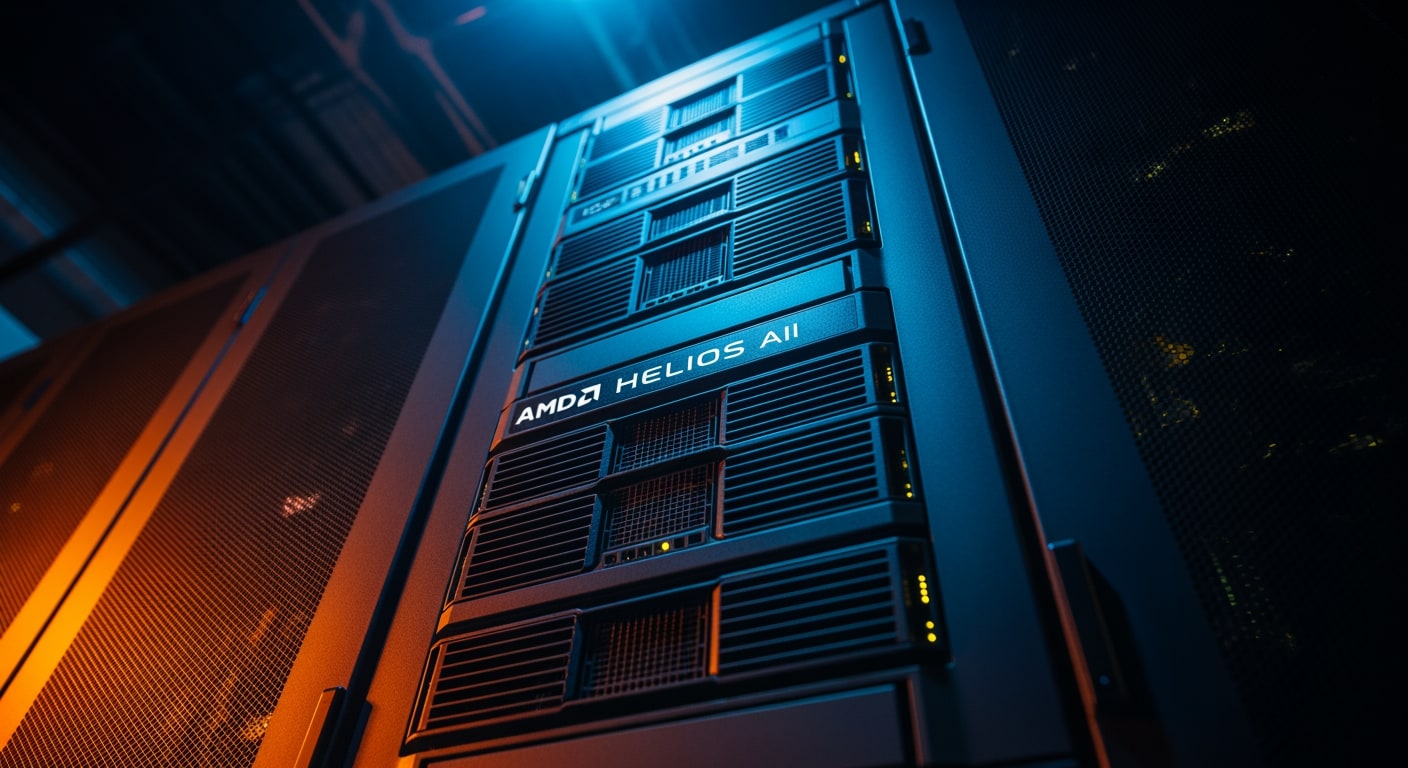
The deals with Anthropic and Core Scientific illustrate the scale at which AMD is betting on AI infrastructure. With Anthropic, AMD concluded an agreement for the deployment of up to 2 gigawatts of MI450-series GPUs in so-called AMD Helios racks. The first gigawatt of capacity is scheduled to go live in early 2027.
With Core Scientific, AMD signed a 15-year strategic agreement valued at more than $14 billion. The agreement gives AMD access to up to 2.5 gigawatts of AI datacenter capacity across multiple locations in the United States. The initial rollout covers approximately 530 megawatts, planned across five U.S. states starting in 2027. Adam Sullivan, CEO of Core Scientific, confirmed the deal.
Both partnerships focus on the physical infrastructure required to run large-scale AI models, a segment where demand has grown strongly over the past several quarters.
Gaming continues to slide
While the datacenter segment posts record figures, the gaming division is contracting once again. A year-on-year decline of 31 percent is significant, though it fits a trend that has been visible for several quarters. The PC gaming market is under pressure from declining consumer spending and a market that is normalising after peaking during the pandemic period.
For AMD as a whole, this means that dependence on datacenter- and AI-related revenue is increasing further. That brings concentration risk, but also reflects where investment in the chip industry is flowing. Nvidia has undergone a comparable shift, though that company still holds a stronger market position in AI chips through its CUDA ecosystem.
What this means for the market
AMD's quarterly figures align with a broader movement in the chip industry: hyperscalers and large AI labs are investing heavily in computing capacity, and chip companies such as AMD are competing to capture a share of that spending. The agreements with Anthropic and Core Scientific are multi-year contracts, pointing to a long-term strategy of tying customers to AMD hardware before Nvidia's dominance in AI chips becomes further entrenched.
The MI450-series GPUs, deployed in the Helios racks, are AMD's answer to Nvidia's H- and B-series accelerators. Whether AMD succeeds with this hardware in gaining market share in a segment that Nvidia has dominated for years will become clear in the coming quarters through adoption figures and customer satisfaction data.
For European datacenter companies and investors in AI infrastructure, this underscores that the market for AI chips is becoming more competitive. AMD is positioning itself through long-term capacity agreements as an alternative to Nvidia, which will also be relevant over time for parties in Europe looking for alternative suppliers or diversification of their hardware stack.