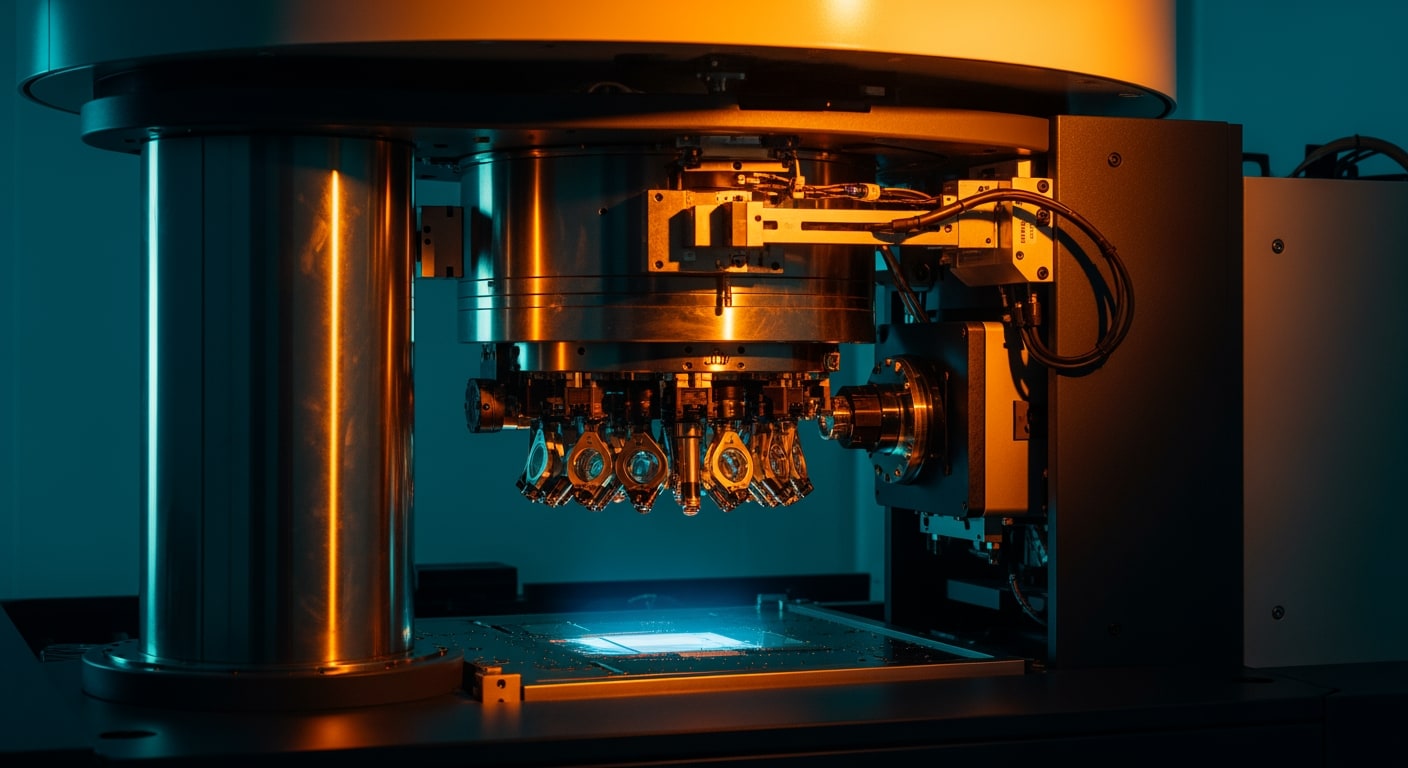
A state-owned company in Shanghai has begun mass production of immersion DUV lithography machines, the type of equipment required for the production of more advanced semiconductors. The Information reported this in July 2026, citing sources who wished to remain anonymous given the sensitivity of the subject. The company is not named in the article.
The machines are not suitable for the most cutting-edge chips, but the step nonetheless represents a milestone for China's semiconductor industry. The country has for years been dependent on Western and Japanese equipment for chip production, and Western export restrictions make that dependence a vulnerability. With its own lithography machines, China aims to gradually reduce that reliance.
Behind the production lies a consolidation of DUV development teams from multiple Chinese companies. A central role is played by Shanghai Yuliangsheng Technology, a state-backed startup with ties to Huawei and the SiCarrier equipment group. Chipmaker SMIC began testing a Yuliangsheng machine as early as September 2025.
Small numbers, significant meaning
Production volumes remain modest for now. Around five machines are expected in 2026, followed by approximately twenty additional units in 2027. By comparison, ASML shipped 131 immersion DUV machines in 2025 alone. Active deployment at SMIC in mass production is being targeted as early as 2027, though that depends heavily on how quickly the machines' quality and reliability can be brought up to standard.
The first deliveries will go to China's three largest chipmakers: SMIC, Hua Hong Semiconductor, and ChangXin Memory Technologies (CXMT). These companies currently have the greatest need for domestic alternatives, as export restrictions largely deny them access to modern Western lithography machines.
Technical capability and comparison with ASML
The Chinese machines are designed for chips in the 28-nanometer class using single exposure. With multi-patterning, in which multiple exposure steps are combined, they can theoretically reach 7nm or even 5nm, though this comes with lower yields and higher per-chip costs.
In terms of technical level, the machines appear comparable to ASML's Twinscan NXT:1950i, a system ASML introduced around 2008 for 32nm work. ASML's current DUV flagship, the TWINSCAN NXT:2150i, has since achieved considerably higher performance and reliability. The Chinese systems therefore trail what ASML delivers today by multiple generations, both in throughput and in precision.
Most components in the new machines are domestically produced, but for a number of critical parts China remains dependent on Japan. That is a vulnerability, particularly now that Japan has also tightened its export rules for semiconductor equipment.
Earlier estimates overtaken by reality
The timing of this news is notable in light of recent analyses. The AI Futures Project estimated in June 2026, virtually simultaneously with The Information's reporting, that commercial Chinese immersion DUV machines would not be expected until the mid-2030s. Actual developments are therefore running at least a decade ahead of that projection.
At the same time, China is also working on EUV lithography, the technology required for today's most advanced chips. Reuters reported in December 2025 on a working prototype of a domestic EUV system. Mass production in that area is not yet in sight, and the technical gap with ASML's EUV machines is considerably larger than in the case of DUV.
Implications for the semiconductor market and Europe
For ASML, which has not been permitted to deliver its DUV machines to Chinese customers for some time due to Dutch and European export restrictions, this news confirms that the restrictions have slowed but not halted China's development. The Veldhoven-based company holds a dominant position in the global market for lithography machines, but the emergence of an alternative, however limited in scale and quality, is a new factor that policymakers and investors may need to take into account.
For the Dutch and European semiconductor strategy, this underscores the tension between export controls as a policy instrument and the long-term position of European suppliers. China is structurally investing in building its own supply chain, and the first results of that effort are now becoming visible. How quickly the quality gap with Western machines narrows will serve as a gauge of the effectiveness of current export policy in the years ahead.