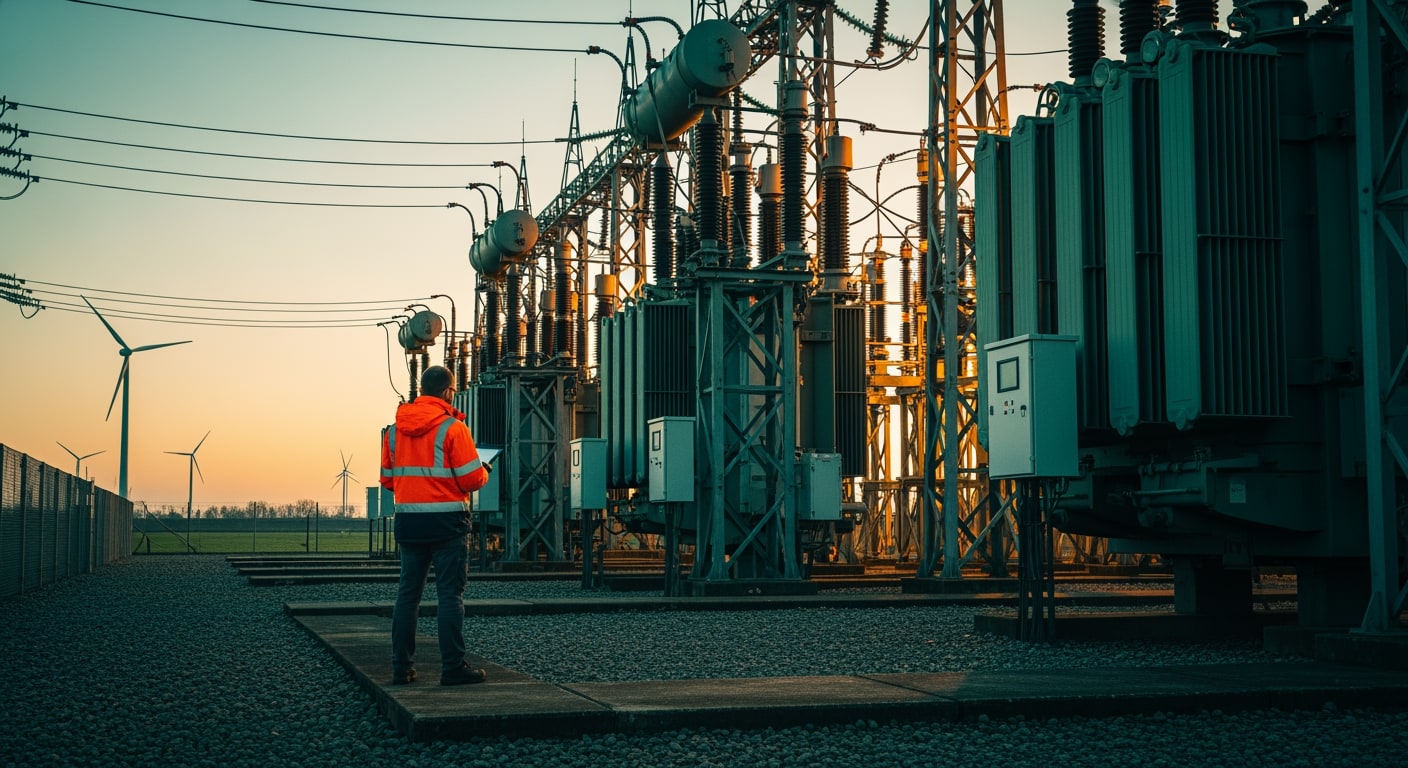
The Dutch energy sector has continued to develop over the past year into one of the most active segments within the national startup scene. More than three dozen companies operate at the intersection of renewable energy, artificial intelligence and infrastructure, with a clear focus on software for grid balancing, smart charging and building optimisation.
Funding flowed freely over the past year: the twelve most heavily funded names in the overview alone represent a combined total of more than four hundred million euros in capital raised. That money comes from European growth funds, pension funds and sector specialists, indicating that institutional investors are taking the market seriously. At the same time, international scaling remains a challenge: most players are strongly focused on Europe and compete there with well-funded alternatives from the United Kingdom and Germany.
Where the largest rounds are going
Sympower and Overstory lead the field in terms of total capital raised, at €74.5 million and €67.8 million respectively. Sympower enables companies to flexibly shift their energy demand, contributing to the balancing of national electricity grids. Overstory combines satellite imagery with AI to alert electricity grid operators to vegetation that threatens power lines.
Eindhoven-based Axelera AI received €61.6 million via an EU grant, intended for the development of energy-efficient AI chips for applications outside the data centre. This is a different form of financing from that used by most other companies in the overview, and reflects the European commitment to semiconductor technology.
Gradyent, based in Rotterdam, closed a Series B of €28 million in 2025. The company builds digital twins of heat networks, enabling operators to see in real time where heat is being lost and how distribution can be made more efficient. Dexter Energy raised €23 million in a Series C in July 2025, led by Alantra's energy transition fund Klima. Dexter provides software for short-term trading in renewable energy and now works with more than eighty energy companies in nine European countries, including Centrica Energy and Luminus. The new capital will go towards battery trading and further geographic expansion.
Smart charging and building optimisation as growing niches
Two segments stand out for the number of players and the size of recent rounds: smart charging of electric vehicles and AI-driven building optimisation.
Arnhem-based Deftpower raised €12.5 million in September 2025 in a round led by Endeit Capital. The platform shifts charging sessions for EV drivers to moments when electricity is cheaper and greener, reducing grid congestion. The company has seventy employees and serves more than forty customers in ten European countries, including Liander, Vattenfall and ANWB.
Next Sense, formed in 2024 from a merger of EDGE Next and Sense by PHYSEE, closed a Series A of €11.5 million, co-financed by pension fund ABP and ETF Partners. The Amsterdam-based company offers a cloud platform that enables property owners to monitor energy consumption and track ESG targets. It is active on more than 150 real estate projects.
Habitat AI, a joint venture between real estate group Larmag and sustainability company Solgen International, raised $16 million in a seed round in July 2025. The company focuses on AI-native data centres powered by renewable energy. Its headquarters are in Santa Monica, though Amsterdam is registered as its founding location.
Geospatial data and weather models as the underlying layer
Several companies in the overview do not deliver a final product to energy companies, but instead form the data foundation on which others build. Weather Solutions (The Hague) provides tailored weather forecasts for energy, mobility and agriculture and already raised €42.3 million in 2022. 52impact (Amersfoort) offers geospatial data that enables companies to map environmental and climate risks, raising €15 million in that same year.
Utrecht-based StellaSpark builds digital twins for monitoring the physical environment and has attracted €50 million in capital to date. Crownstone, active in Rotterdam, focuses on battery-free indoor positioning, a technology that can also be applied to building energy management.
These data companies are less visible than platforms that sell directly to grid operators or energy producers, but they form an essential part of the chain. Without accurate weather and location data, forecasting models perform less effectively.
Challenges: grid congestion, regulation and scalability
The sector operates in an environment of persistent grid congestion. In large parts of the Netherlands, new connection slots for solar and wind projects can take months to years to obtain. On one hand, this creates demand for software that makes better use of existing capacity, benefiting companies such as Dexter Energy and Sympower. On the other hand, it slows the rollout of new installations from which startups earn revenue.
European regulation around energy flexibility and data exchange is evolving rapidly, but varies from country to country. Companies operating in multiple markets, such as Deftpower and Dexter Energy, must build integrations for divergent market structures. This takes time and money, and slows scaling.
Most companies in this overview are still loss-making or do not disclose profitability figures. How quickly they can grow towards profitability depends heavily on contract lengths, customer retention and the willingness of governments and grid operators to enter into long-term agreements.
For investors and policymakers elsewhere in Europe, the Dutch concentration of energy-AI companies provides a reference point. The combination of a dense energy infrastructure, active grid operators such as Liander and TenneT, and a relatively open attitude towards pilot projects has given several companies the opportunity to test early and then expand internationally. Whether that advantage will persist as comparable ecosystems in Germany and Scandinavia gain momentum remains to be seen.