The Dutch startup sector in sustainability and climate now counts 36 companies, most of which focus on energy management, grid congestion and data infrastructure for the energy transition. The combined funding of the eleven most-funded players already exceeds 340 million euros, with rounds closed in 2024 and 2025.
What stands out in the field is the concentration: almost all companies combine energy with AI, and most are based in Amsterdam, though Rotterdam, Arnhem, Eindhoven and The Hague are also represented. The sector is therefore no longer exclusively a Randstad affair. At the same time, the market is still young: several companies are in an early stage, while a handful of frontrunners have already surpassed one hundred million euros in cumulative funding.
Two frontrunners with Series B rounds in the tens of millions
Sympower and Overstory are the best-funded companies in the overview, having raised 74.5 million and 67.8 million euros respectively, both through a Series B round. Sympower, founded in 2015 in Amsterdam, focuses on energy flexibility for businesses and helps national electricity grids stay in balance by matching supply and demand. This is directly linked to the grid congestion problem that has been affecting the Netherlands for years.
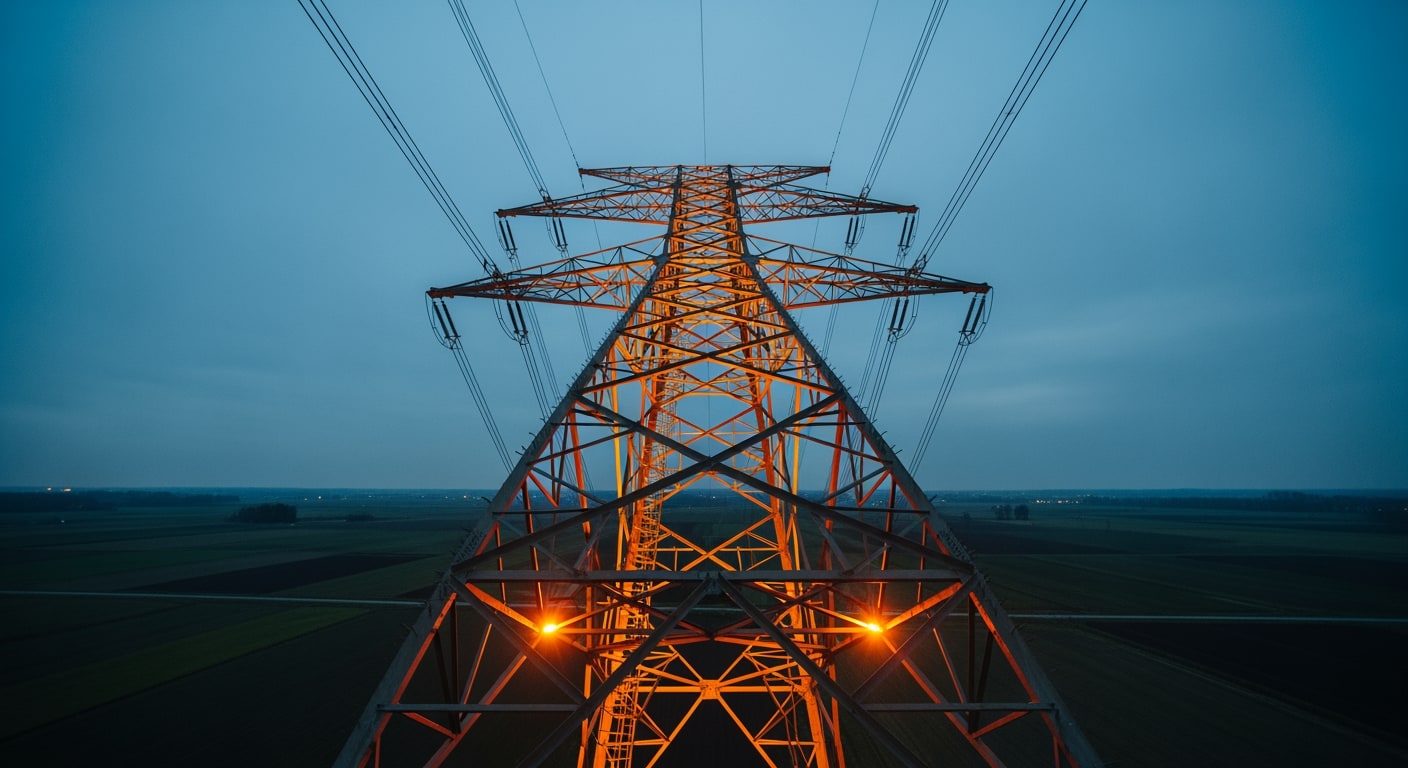
Overstory combines satellite imagery with AI to protect electricity networks against tree growth and vegetation along high-voltage lines. The company, also from Amsterdam, is one of the few Dutch climate startups with a clear focus on grid management and infrastructure safety rather than energy production or storage.
StellaSpark (Utrecht, founded 2015) raised 50 million euros through an equity round in 2023 and provides digital twins for the management and monitoring of the physical environment. Weather Solutions in The Hague closed a Series B of 42.3 million euros in 2022 and supplies tailored weather data for energy, mobility and agriculture, sectors that are each becoming increasingly dependent on accurate climate information.
AI and digital twins dominate the approach
Of the eleven companies discussed here, nine explicitly combine their core product with AI. This is no coincidence. The energy transition generates enormous volumes of data, from charging stations and solar panels to heat networks and grid balancing, and that data is only useful if it is processed quickly and automatically.
Gradyent (Rotterdam, founded 2019) raised a Series B of 28 million euros in January 2025 and builds digital twins for heat networks. This technology calculates in real time how heat can flow most efficiently through a network, reducing both energy loss and CO2 emissions. Dexter Energy (Amsterdam, founded 2017) closed a Series C of 23 million euros, also in January 2025, and provides integrated software for trading and forecasting in renewable energy.
Next Sense, a young Amsterdam-based company founded in 2024, has already raised 11.5 million euros through a Series A and is developing AI solutions for energy and climate. The fact that such a young company has already closed a Series A points to sustained investor appetite in this segment. Habitat AI, also from Amsterdam and founded in 2025, raised 16 million euros in seed capital, making it one of the larger seed rounds in the sector.
Grid congestion as a structural market driver
Several companies in this overview focus, directly or indirectly, on the grid congestion problem. The Netherlands has been dealing with overloaded electricity networks for several years, which delays connections for businesses and complicates the integration of renewable energy. That same problem simultaneously creates a market for technology that enables flexibility, control and optimisation.
Tibo Energy (Eindhoven, founded 2022) focuses specifically on energy management for businesses with the aim of preventing grid congestion and reducing energy costs. The company raised a seed round of 6 million euros in 2025. Deftpower (Arnhem, founded 2020) builds a smart charging platform for electric vehicles and raised 12.5 million euros through a growth round in 2025. Smart charging, aligning charging moments with grid load, is one of the most direct ways to limit congestion at the local level.
Sympower addresses the same issue at the national level, deploying corporate flexibility as a balancing instrument for grid operators. This requires contracts with both large industrial consumers and grid operators, an approach that takes more time but also delivers greater systemic value.
Geospatial data and environmental monitoring as a distinct niche
Not all companies focus on the electricity grid. A segment of the sector works on data infrastructure for broader sustainability challenges. 52impact (Amersfoort, founded 2017) uses geospatial data to help businesses map and manage environmental and sustainability risks. The company raised a Series B of 15 million euros in 2022.
Overstory falls into a similar category: satellite data as a means of managing risks to physical infrastructure. Weather Solutions adds weather data to this, with applications ranging from energy forecasting to crop planning in agriculture. Together, these companies form a layer of data services on which other parties in the chain can build.
StellaSpark connects to this with its platform for monitoring the physical environment, with applications in public space and infrastructure management. With 50 million euros in funding, it is one of the more heavily funded players outside the direct energy segment.
Challenges for the sector in 2026
The sector faces a number of concrete issues. First, the market for many of these products is heavily dependent on regulation. Energy flexibility, smart charging and grid optimisation only work if the legal frameworks and tariff structures are aligned, and these are still evolving in the Netherlands and across Europe.
Second, scale is a challenge. Several companies, including Gradyent and Sympower, already operate in multiple European countries, but for many other players in the overview, international growth remains a next step. The Dutch market is relatively small for products that depend on network effects or long sales cycles with grid operators and energy companies.
Third, there is the question of capital continuity. Seed and Series A rounds have been readily accessible in recent years, but the transition to later growth stages has become more difficult for climate tech globally. Companies such as Tibo Energy and Deftpower are at that crossroads.
For the Dutch AI and startup scene as a whole, the concentration of climate tech activity around energy management and grid optimisation is notable. It connects to a concrete national infrastructure problem and attracts capital from both domestic and foreign funds. Whether the sector can meet the expectations of those investors will depend in part on how quickly the energy market and regulation adapt to the technological capabilities these companies offer.