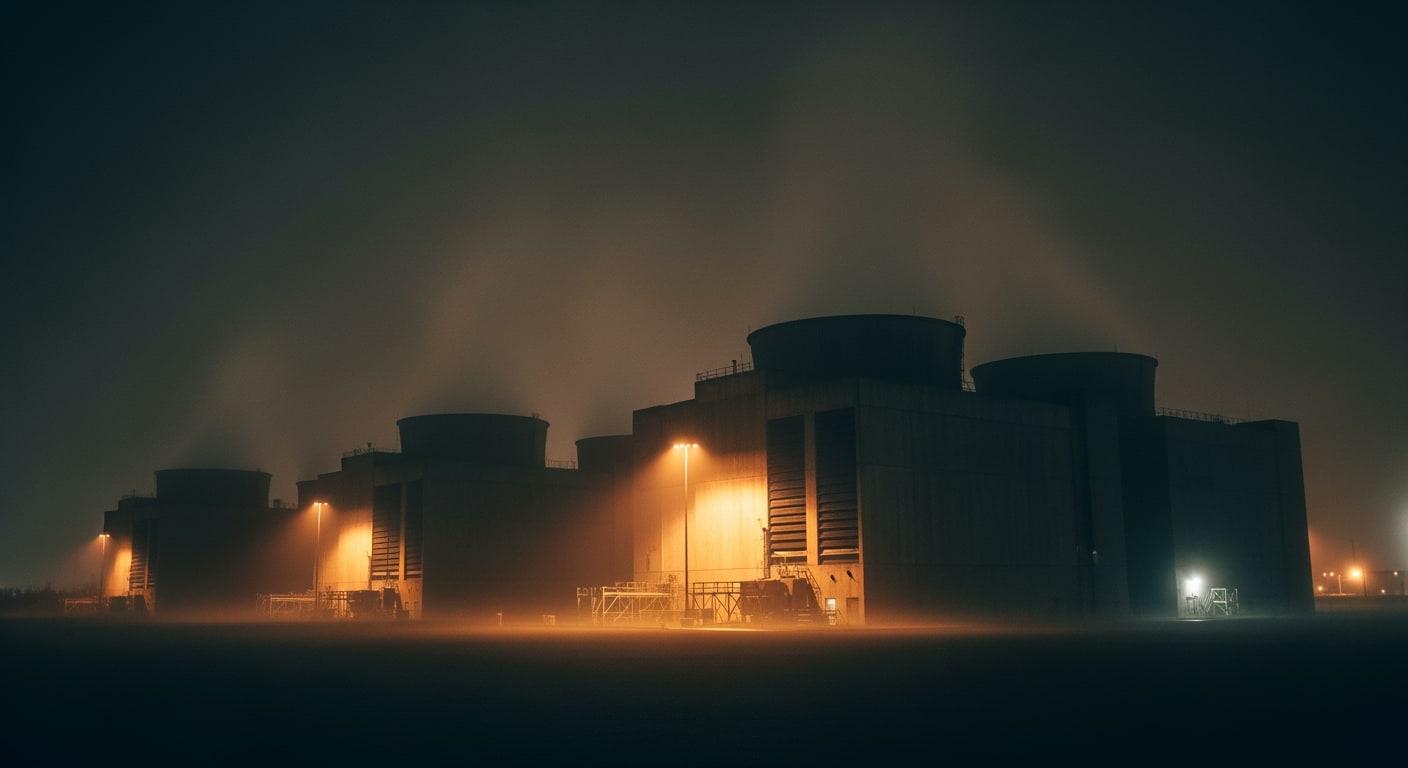
Data centers in the United States currently consume around 5 to 6 percent of all electricity in the country. According to a new report by BloombergNEF (BNEF), that share is expected to rise to approximately 20 percent by 2035, a fourfold increase compared with current levels. Growth is driven primarily by the rapidly expanding use of AI applications, which require significantly more computing power than traditional software.
To put the scale of the anticipated expansion in concrete terms: new data centers built through 2033 could collectively consume as much electricity as India uses today. That gives some indication of how quickly the sector is growing. The report was co-authored by Lloyd Arnold, analyst at BNEF, and Mark Daly, head of technology and innovation at the research firm.
AI as the primary driver of electricity demand
The BNEF report points above all to the rise of AI applications as the explanation for the expected growth. As AI applications are scaled up, more computing power is required, and that computing power demands electricity. This creates a paradox increasingly noted within the industry: individual AI models are becoming more efficient, yet total system demand is rising at the same time. In other words, efficiency gains at the model level do not automatically translate into a lower energy bill for the sector as a whole.
An illustration of this is the Kimi K3 model from Chinese company Moonshot AI, released in July 2026. The model improves computational efficiency compared with previous generations, but simultaneously requires a larger architecture and heavier memory infrastructure. On balance, pressure on the power supply does not diminish as a result.
Chipmakers and suppliers such as Nvidia, SK Hynix and TSMC play a central role in the expansion. They supply the chips and memory components needed for modern AI models, and demand for their products is pulling the construction of new data centers along with it.
Bitcoin miners reorient toward AI computing
A notable development in the US market is the shift from bitcoin mining to AI computing. Companies such as Core Scientific and Riot Platforms, traditionally active in crypto mining, are converting their facilities for AI workloads and partnering with parties such as AWS and Google to do so.
This reorientation makes sense given their position. Existing mining facilities already have heavy-duty power connections, which normally take years to arrange. By repurposing that infrastructure for AI computing, they can offer capacity more quickly than new-build projects. At the same time, the revenue stability of AI contracts is more attractive to many of these companies than the volatility of crypto prices.
Grid operators face a capacity challenge
The anticipated growth presents grid operators with concrete challenges. The electricity grid in the US varies considerably by region in terms of capacity and reliability. In areas where data centers are concentrated, available grid capacity is sometimes already stretched to its limits. Growing AI demand is making those bottlenecks more pressing.
Data center operators, energy companies and local governments will need to reach agreements in the coming years about who makes which investments in grid reinforcement and who bears the cost. That debate is playing out not only in the US but also in Europe, where similar discussions are taking place about the allocation of grid capacity between large consumers and households.
Relevance for the Dutch and European AI scene
For Dutch and European AI companies, the BNEF figures are worth factoring into their calculations. The Netherlands hosts a concentration of large data centers, particularly around Amsterdam, partly due to its favorable location and the presence of AMS-IX, one of the largest internet exchange points in the world. The Amsterdam municipality and the province of Noord-Holland have previously imposed temporary restrictions on the construction of new hyperscale data centers, precisely because of the pressure on power supply and land use.
If the US does move toward 20 percent electricity consumption by data centers by 2035, the debate over site selection, energy mix and grid capacity will intensify in Europe as well. Founders planning infrastructure, investors entering data center-related businesses and policymakers granting permits will all face the same fundamental question: where does the electricity come from, and who bears the cost of the required grid expansion.